AI-generated illustration
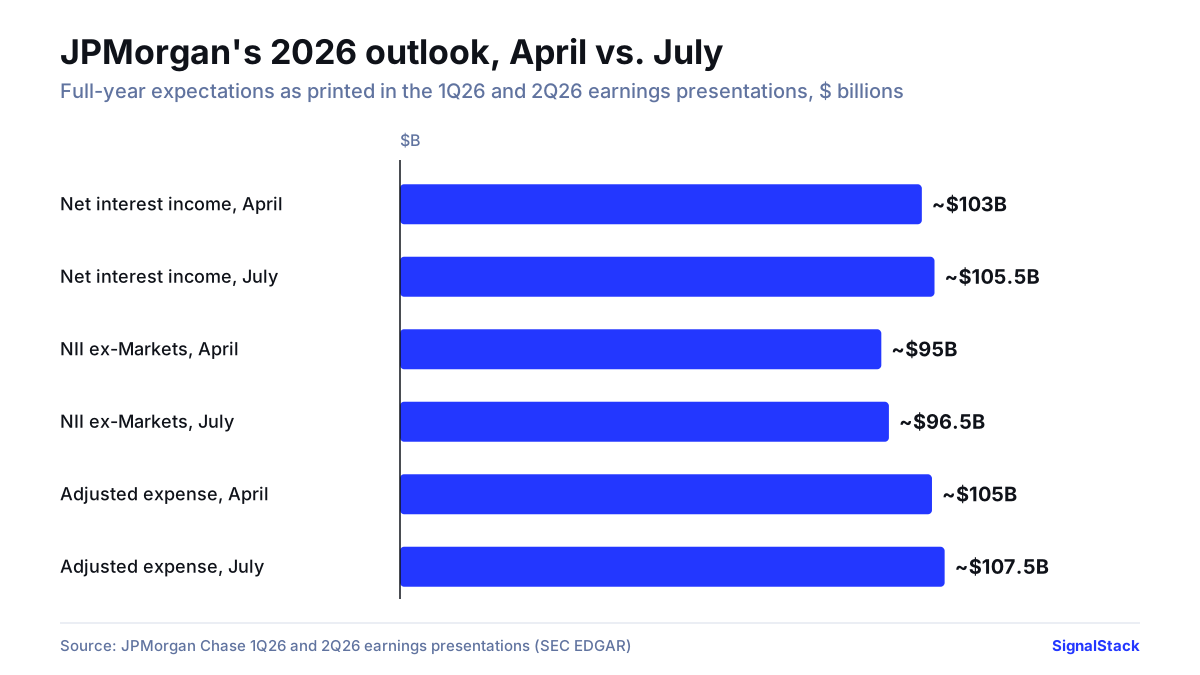
TL;DR: Four of the six largest U.S. banks (JPMorgan Chase, Goldman Sachs, Wells Fargo and Citigroup) publish third-quarter 2026 results on Tuesday, Oct. 13, all before the U.S. stock market opens. Bank of America and Morgan Stanley follow on Oct. 14. Three of the four already put full-year numbers on paper. In July, JPMorgan raised its full-year net interest income outlook to about $105.5 billion, from about $103 billion in April. Wells Fargo kept its outlook of roughly $50 billion. Citi set a 10–11% return target for 2026, and its CFO later said he expected to slightly exceed it. Below are the dates, those printed outlooks side by side, and what executives said at investor conferences in September, so the Oct. 13 releases can be read against what each bank said itself.
When each bank reports
All times are U.S. Eastern and come from each bank’s own announcement. You can also follow them on our Q3 2026 earnings calendar.
| Bank | Date | Results out | Call or webcast |
|---|---|---|---|
| JPMorgan Chase (earnings page) | Tue, Oct. 13 | about 7:00 a.m. | 8:30 a.m. |
| Wells Fargo (earnings page) | Tue, Oct. 13 | about 7:00 a.m. | 10:00 a.m. |
| Goldman Sachs (earnings page) | Tue, Oct. 13 | about 7:30 a.m. | 9:30 a.m. |
| Citigroup | Tue, Oct. 13 | about 8:00 a.m. | 11:00 a.m. |
| Bank of America (earnings page) | Wed, Oct. 14 | about 6:45 a.m. | 8:30 a.m. |
| Morgan Stanley (earnings page) | Wed, Oct. 14 | about 7:30 a.m. | 9:30 a.m. |
For the second quarter, JPMorgan, Wells Fargo and Citi each posted their results release on SEC EDGAR as Exhibit 99.1 to an 8-K. Our guide to earnings season filings explains what each document contains.
What each bank printed about 2026
These are the full-year expectations the banks published with their second-quarter results on July 14, in their own words. Goldman Sachs did not give a numeric full-year outlook in its release.
| Bank | What it said it expects for full-year 2026 | Change from the previous outlook |
|---|---|---|
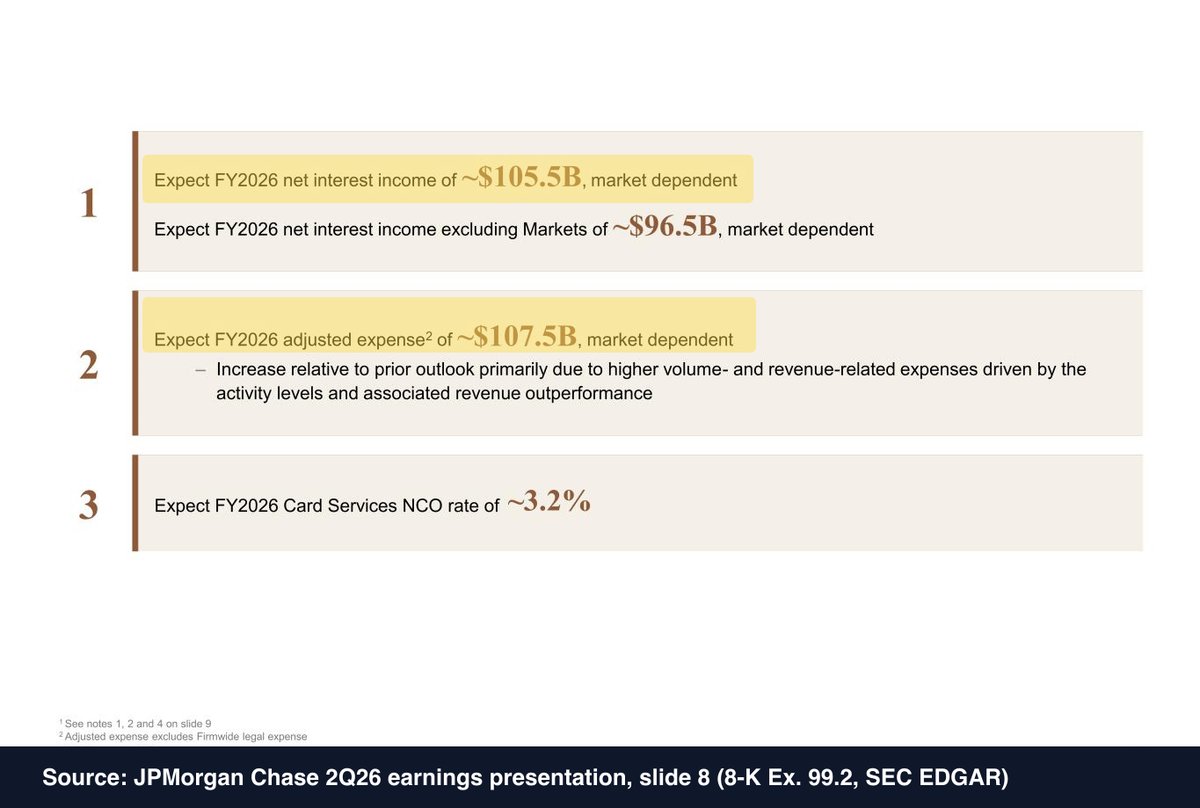
| JPMorgan Chase | Net interest income of ~$105.5B; ex-Markets ~$96.5B; adjusted expense of ~$107.5B; Card Services net charge-off rate of ~3.2% | Raised from ~$103B, ~$95B and ~$105B; card loss rate lowered from ~3.4% (April outlook) |
| Wells Fargo | Net interest income of ”+/- $50 billion”; noninterest expense of ”~$55.7 billion” | Both “unchanged from prior guidance” |
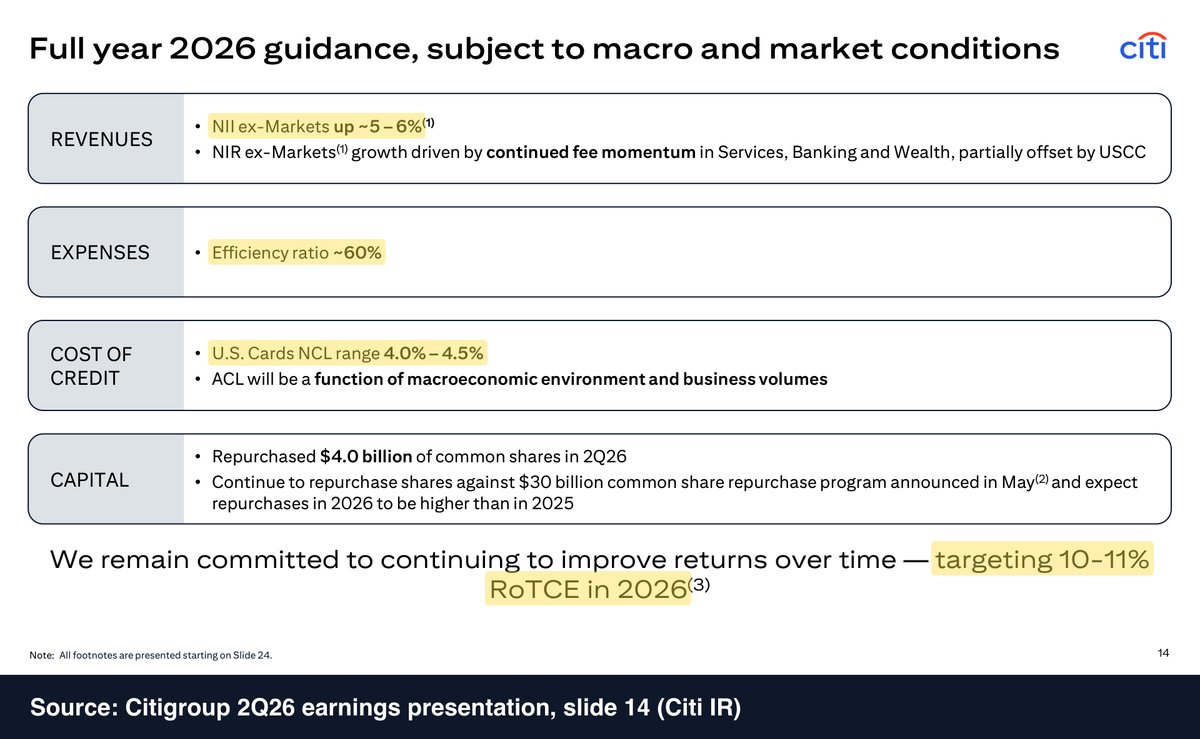
| Citigroup | Net interest income excluding Markets up ~5–6%; efficiency ratio ~60%; U.S. Cards net credit loss rate of 4.0%–4.5%; “targeting 10-11% RoTCE in 2026” | Framed as “subject to macro and market conditions” |
| Goldman Sachs | No numeric full-year outlook in the release | n/a |
JPMorgan’s slide labels each figure except the card loss rate “market dependent.” The bank says the higher expense outlook mainly reflects volume- and revenue-related costs that came with stronger activity.
The June quarter, the base Oct. 13 is compared with
| Bank | Q2 2026 net income | Diluted EPS | Revenue |
|---|---|---|---|
| JPMorgan Chase | $21.2B ($16.9B excluding significant items) | $7.70 ($6.14 ex. items) | $57.3B reported |
| Goldman Sachs | $6.63B | $20.98 | $20.34B net revenues |
| Wells Fargo | $6.4B | $2.00 | $22.6B |
| Citigroup | $5.8B | $3.15 | $24.8B |
JPMorgan’s headline figure included significant items, so the bank also reported net income without them. Its investment banking fees rose 30% from a year earlier and its markets revenue rose 35%. Citi said its net income rose 45%.
What executives said in September
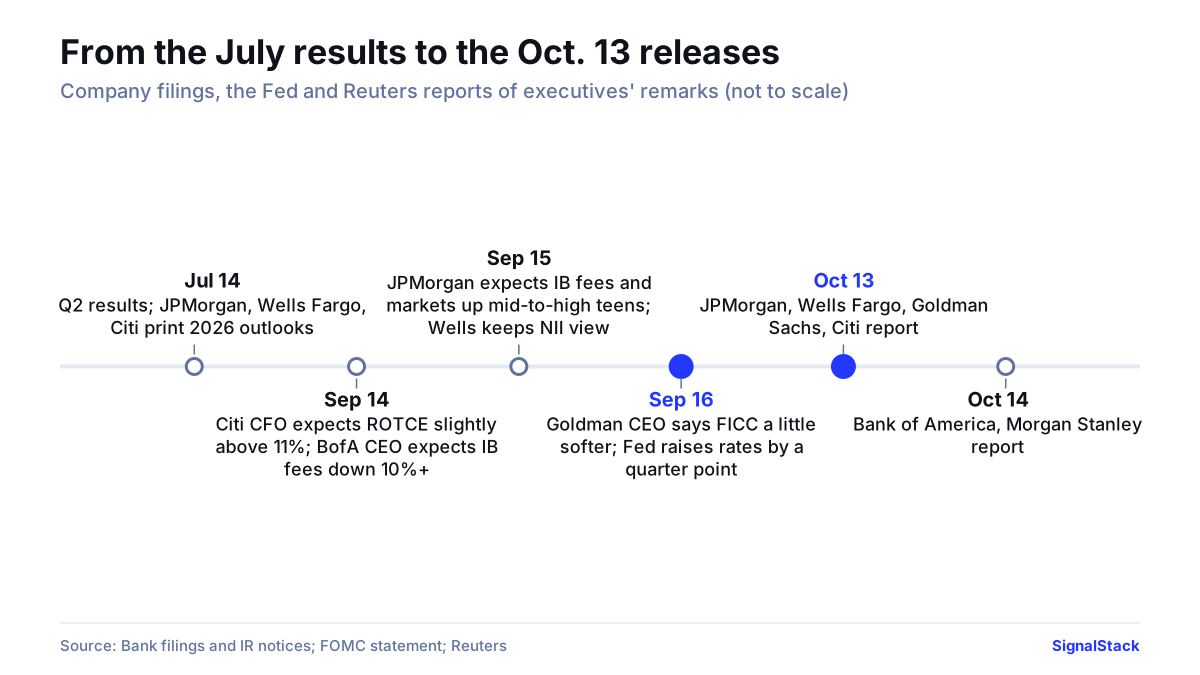
Reuters reported these remarks from investor conferences in mid-September, most of them at the Barclays Global Financial Services Conference. They are not filings, but they are recent on-record comments before the results.
- JPMorgan: co-President Doug Petno said he expected investment banking fees and markets revenue to rise by a “mid-to-high teens” percentage in the third quarter.
- Wells Fargo: CFO Mike Santomassimo said he expected loan growth in 2026 to be better than the earlier mid-single-digit forecast. He kept the NII and expense outlooks and said the bank was not seeing deterioration in delinquency trends. Reuters reported that the bank anticipates investment banking fees and markets revenue to grow by mid-single digits in the quarter.
- Goldman Sachs: CEO David Solomon told the conference that FICC (fixed income, currencies and commodities) had been “a little bit softer on a relative basis,” while equities remained “very strong.” He said non-compensation expenses would be $500 million higher, and, per Reuters, warned that the firm’s investment line would be much quieter in the third quarter after a busy second quarter.
- Citigroup: CFO Gonzalo Luchetti said the bank expected its return on tangible common equity to come in slightly above 11% this year, just above the top of its printed 10–11% range. He also said buybacks would exceed the $13 billion repurchased in 2025.
- Bank of America (reports Oct. 14): CEO Brian Moynihan said in September he expected the bank’s investment banking fees to drop at least 10% in the quarter, with sales and trading revenue roughly flat, Reuters reported.
Background: a rate increase late in the quarter
On Sept. 16 the Federal Reserve raised the federal funds target range by a quarter point, to 3.75%–4%. Reuters’ Oct. 8 preview said investors would focus on whether higher rates push up deposit costs and weaken credit quality. It also noted that bond-yield moves contributed to IPO postponements late in September, including those of Oura and SB Energy.
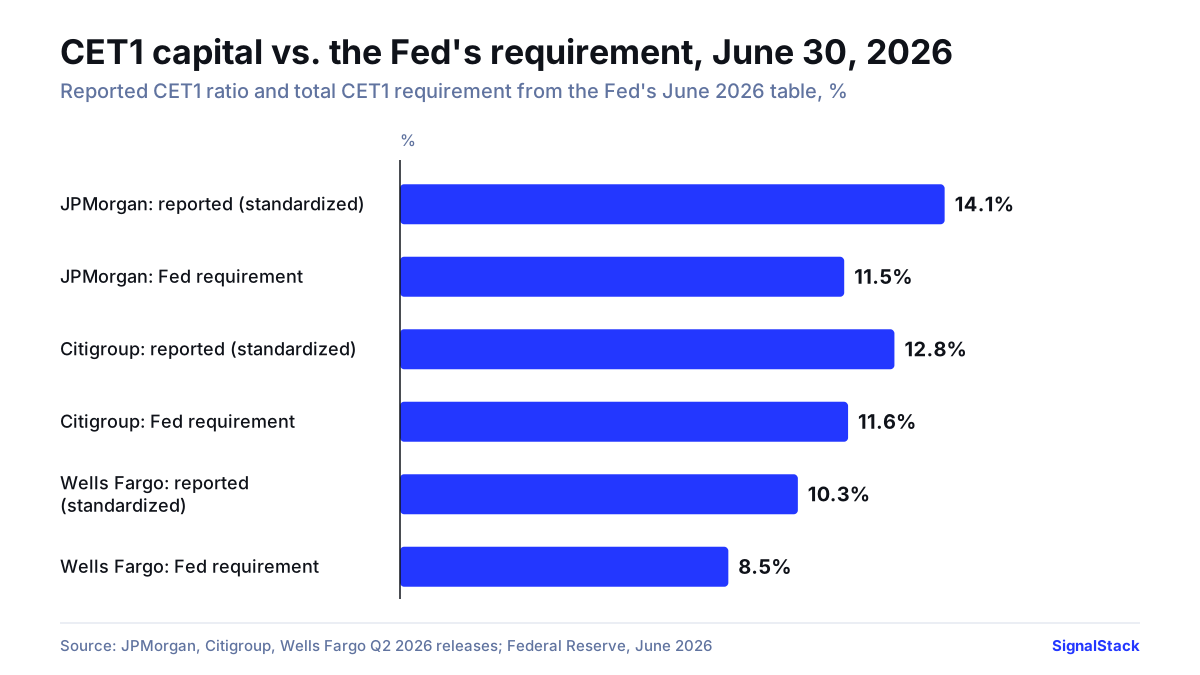
Capital is the other thread. The Fed kept each bank’s stress capital buffer unchanged until 2027, so the buffers set in 2025 still apply. Added to the 4.5% minimum and any GSIB surcharge, they make up each bank’s total common equity tier 1 (CET1) requirement in the Fed’s June 2026 table:
| Bank | Stress capital buffer | GSIB surcharge | Total CET1 requirement |
|---|---|---|---|
| JPMorgan Chase | 2.5% | 4.5% | 11.5% |
| Goldman Sachs | 3.4% | 3.5% | 11.4% |
| Wells Fargo | 2.5% | 1.5% | 8.5% |
| Citigroup | 3.6% | 3.5% | 11.6% |
| Bank of America | 2.5% | 3.0% | 10.0% |
| Morgan Stanley | 4.3% | 3.0% | 11.8% |
At the end of June, JPMorgan reported a standardized CET1 ratio of 14.1%, Citi 12.8% and Wells Fargo 10.3%. Each is above its Fed requirement. JPMorgan raised its quarterly dividend to $1.65 from $1.50 in September.
What could go right / What could go wrong
What could go right, going by what the banks have said themselves:
- JPMorgan co-President Doug Petno pointed to fee and trading growth in the “mid-to-high teens” for the quarter, and the bank raised its full-year NII outlook in July.
- Wells Fargo’s CFO said he expected loan growth to beat the earlier mid-single-digit forecast and saw no deterioration in delinquencies.
- Citi’s CFO put the 2026 return slightly above the top of its own range.
What could go wrong, going by the same record:
- Goldman’s CEO flagged softer FICC, a more muted quarter for the firm’s investment line, and $500 million in higher non-compensation expenses.
- Bank of America’s CEO expected investment banking fees to fall at least 10%.
- Reuters reported that investors would watch whether higher rates drive up deposit costs or weaken credit quality.
- JPMorgan raised its own expense outlook by about $2.5 billion, to ~$107.5 billion, which the bank tied to higher volume- and revenue-related costs.
On Oct. 13, the plainest test is whether each bank keeps, raises or cuts the full-year numbers in the table above, and whether the third-quarter fee and trading figures match the ranges executives gave in September.
FAQ
Q When do the big banks report Q3 2026 earnings?
A JPMorgan Chase, Goldman Sachs, Wells Fargo and Citigroup report on Tuesday, Oct. 13, 2026, before the U.S. market opens. Bank of America and Morgan Stanley report on Wednesday, Oct. 14.
Q What time does JPMorgan release its Q3 2026 earnings?
A JPMorgan says results come out at about 7:00 a.m. ET on Oct. 13, 2026, with the earnings call at 8:30 a.m. ET.
Q What is JPMorgan's 2026 net interest income guidance?
A In July JPMorgan said it expects full-year 2026 net interest income of about $105.5 billion, "market dependent," up from about $103 billion in its April outlook. Excluding Markets, it expects about $96.5 billion.
Q What did Wells Fargo say about 2026 net interest income?
A Wells Fargo said it expects 2026 net interest income of "+/- $50 billion" and noninterest expense of about $55.7 billion, both unchanged from its prior guidance. Its CFO kept both outlooks in September, Reuters reported.
Q What is Citi's 2026 RoTCE target?
A Citi's July presentation says it is "targeting 10-11% RoTCE in 2026." In September, CFO Gonzalo Luchetti said the bank expected a return slightly above 11%, Reuters reported.
Companies in this report: JPMorgan Chase , Goldman Sachs , Wells Fargo , Bank of America , Morgan Stanley
Sources
- JPMorganChase second-quarter 2026 earnings release (8-K Ex. 99.1)
- JPMorganChase 2Q26 earnings presentation (8-K Ex. 99.2)
- JPMorganChase 1Q26 earnings presentation
- Goldman Sachs second quarter 2026 earnings results
- Wells Fargo second quarter 2026 earnings release (8-K Ex. 99.1)
- Wells Fargo 2Q26 quarterly supplement presentation (8-K Ex. 99.3)
- Citigroup second quarter 2026 results (8-K Ex. 99.1)
- Citi 2Q26 earnings presentation
- JPMorganChase to host third-quarter 2026 earnings call
- Goldman Sachs conference call dates for 4Q25 and 2026 earnings results
- Wells Fargo to announce third quarter 2026 earnings on Oct. 13, 2026
- Citi third quarter 2026 earnings call
- Bank of America announces 2026 financial reporting dates
- Morgan Stanley third quarter 2026 investor conference call
- Large Bank Capital Requirements (June 2026)
- FOMC statement (Sept 16, 2026)
- JPMorgan expects investment banking, trading to shine in third quarter
- Wells Fargo CFO sees stronger 2026 loan growth, healthy US economy
- Goldman Sachs sees slightly softer fixed income, currencies, commodities business, higher costs
- Citigroup CFO Luchetti expects equity return above 11% this year
- U.S. bank investors to focus on impact of higher rates, deals outlook in third-quarter earnings