AI-generated illustration
TL;DR
- TSMC reported third-quarter 2026 revenue of US$46.72 billion (NT$1,494.24 billion) on Oct. 15, above the US$44.6 billion to US$45.8 billion it guided to in July, according to the earnings release it filed with the SEC.
- Of the three ranges TSMC set in July, revenue came in above the top, gross margin (66.4%) landed inside its 65%–67% range, and operating margin (58.7%) came in above its 56%–58% range. The average exchange rate was 31.98 NT dollars per US dollar, against the 32.0 it assumed.
- For the fourth quarter, management expects revenue of US$52.3 billion to US$54.3 billion. It now expects 2026 revenue to grow by around 44% in US dollar terms; in July the figure was “slightly above 40%.” The 2026 capital budget stayed at US$60 billion to US$64 billion.
Net income was NT$763.06 billion and diluted EPS NT$29.43, or US$4.60 per ADR unit, both up 68.7% from a year earlier. TSMC’s report date and the rest of the season’s reporters are on our Q3 2026 earnings hub. More chip coverage: AI & Semiconductors.
What did TSMC report for Q3 2026?
TSMC reports in NT dollars under TIFRS and also states revenue in US dollars. Figures below are from the release (Exhibit 99.1) and slides (Exhibit 99.2) attached to the Oct. 15 Form 6-K; the release notes the board had not yet approved them.
| 3Q26 | 2Q26 | 3Q25 | Change vs 3Q25 | |
|---|---|---|---|---|
| Revenue (US$) | $46.72B | $40.20B | $33.10B | +41.2% |
| Revenue (NT$) | NT$1,494.24B | NT$1,270.38B | NT$989.92B | +50.9% |
| Gross margin | 66.4% | 67.7% | 59.5% | +6.9 pts |
| Operating margin | 58.7% | 60.3% | 50.6% | +8.1 pts |
| Net income (NT$) | NT$763.06B | NT$706.56B | NT$452.30B | +68.7% |
| Diluted EPS (NT$) | 29.43 | 27.25 | 17.44 | +68.7% |
| Average NT$ per US$ | 31.98 | 31.60 | 29.91 | — |
Growth was 41.2% in US dollars but 50.9% in NT dollars. The slide’s exchange-rate row explains the gap: the US dollar averaged 31.98 NT dollars in the quarter, against 29.91 a year earlier.
Net profit margin was 51.1%, down from 55.6% in the second quarter. Non-operating items were NT$34.59 billion, against NT$95.83 billion in the second quarter.
Yahoo Finance reported that net profit topped a NT$746.3 billion consensus estimate based on Reuters/LSEG data. The comparison below uses TSMC’s own July guidance instead.
Results vs. the July guidance
On July 16, TSMC’s second-quarter release said management expected third-quarter revenue of US$44.6 billion to US$45.8 billion. Based on an exchange rate assumption of 32 NT dollars to the US dollar, it expected gross margin of 65% to 67% and operating margin of 56% to 58%. The October slide prints those ranges next to the result.
| Item | July guidance for 3Q26 | 3Q26 actual | Where it landed |
|---|---|---|---|
| Revenue | US$44.6B–45.8B | US$46.72B | $0.92B above the top (our arithmetic) |
| Gross margin | 65%–67% | 66.4% | Inside the range |
| Operating margin | 56%–58% | 58.7% | 0.7 pts above the top |
| Exchange rate (NT$ per US$) | 32.0 assumed | 31.98 average | — |
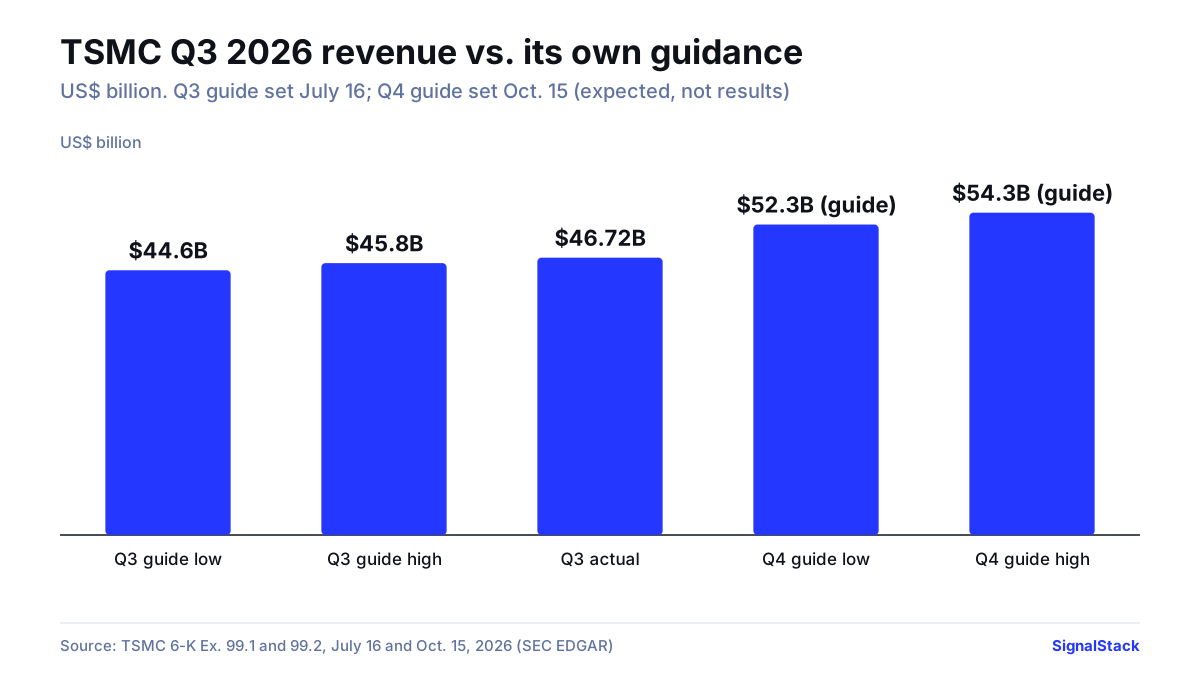
On the Oct. 15 call, CFO Wendell Huang said revenue was “above the high end of our third-quarter guidance.” He put the 1.3-point drop in gross margin from the second quarter mainly down to “margin dilution from 2 nm ramp.” Operating expenses were 7.8% of revenue, he said. (Call quotes in this report are from the Motley Fool transcript.)
Revenue by technology and platform
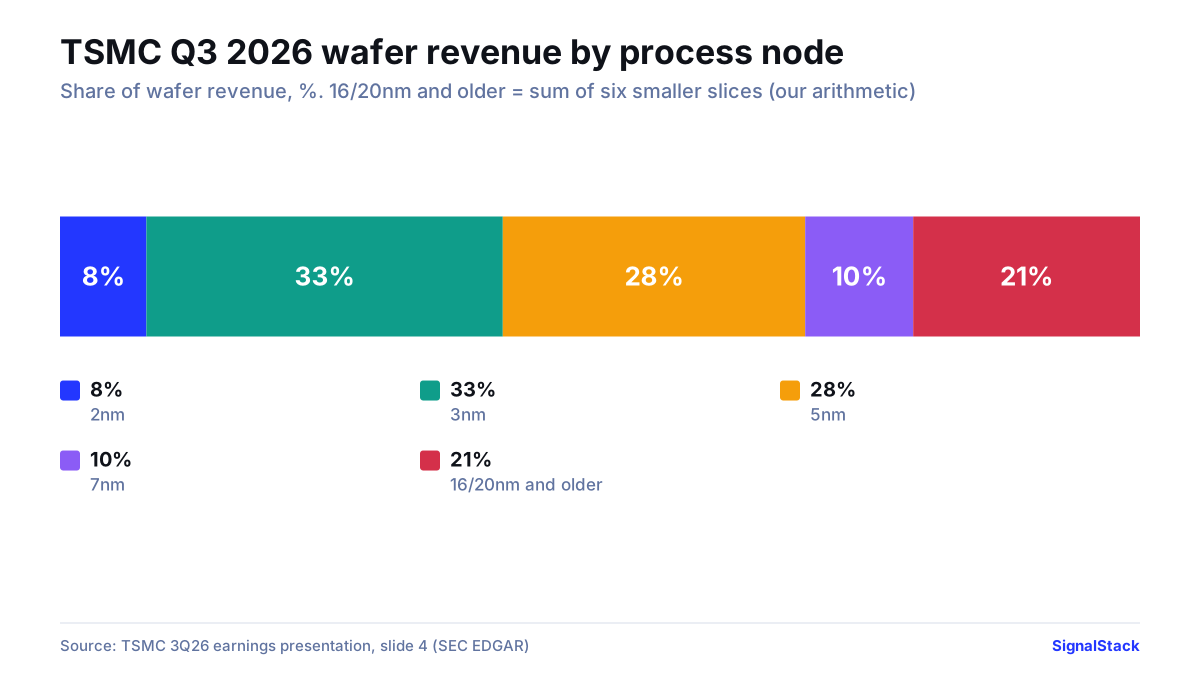
TSMC splits wafer revenue by process node. The 2-nanometer node, which Chairman and CEO C.C. Wei said entered high-volume manufacturing in the fourth quarter of 2025, rose to 8% of wafer revenue from 3% in the second quarter.
| Node | 2Q26 share of wafer revenue | 3Q26 share |
|---|---|---|
| 2nm | 3% | 8% |
| 3nm | 30% | 33% |
| 5nm | 33% | 28% |
| 7nm | 11% | 10% |
| 7nm and below (“advanced”) | 77% | 79% |
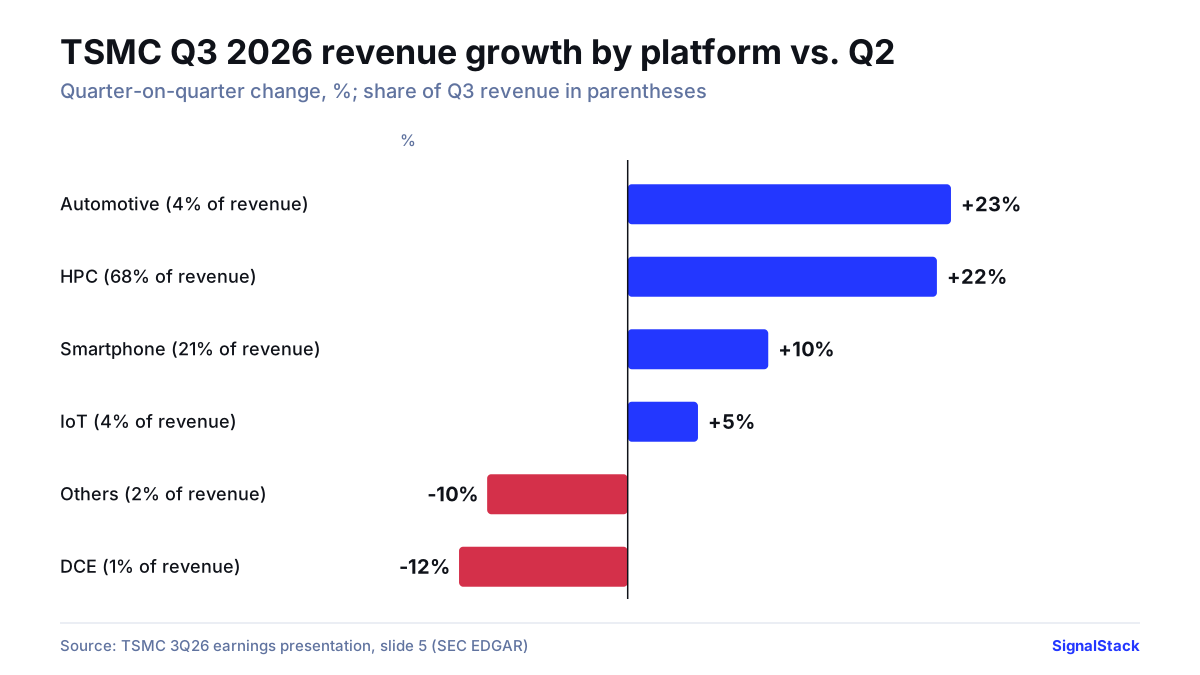
By platform, TSMC’s slide puts high-performance computing (HPC) at 68% of third-quarter revenue, up from 66% in the second quarter. Smartphone was 21%, IoT 4%, automotive 4%, digital consumer electronics (DCE) 1% and others 2%. The slide also gives each platform’s growth from the second quarter.
What does TSMC expect for Q4 and for 2026?
The fourth-quarter guidance, in TSMC’s words on slide 8: “Based on our current business outlook, management expects” revenue “to be between US$52.3 billion and US$54.3 billion.” Based on an exchange rate assumption of 31.8 NT dollars to the US dollar, it expects gross margin of 65% to 67% and operating margin of 56.5% to 58.5%.
Huang said the revenue range represents a 14% sequential increase, or 58% from a year earlier, at the midpoint. He said the gross margin guide implies a 40-basis-point decline to 66% at the midpoint. He tied that mainly to continued dilution from the steep 2-nanometer ramp and from overseas fabs, which TSMC expects to be partly offset by cost improvement efforts.
For the full year, the October “Future Outlook” slide says management expects “2026 revenue to increase by around 44% in US dollar terms.” The July slide said “slightly above 40%.”
On capital spending, Huang said: “we reiterate our full year 2026 capital budget to be between $60 billion and $64 billion,” the range set when TSMC raised the budget in July, per MarketBeat’s summary of that call. Third-quarter capital expenditures were NT$443.21 billion, which Huang gave as US$13.8 billion. In his prepared remarks, Huang said TSMC continues to expect capex from 2026 to 2028 to be “even more significantly higher than the past three years.” Asked in the Q&A about 2027 and 2028, he said: “It’s a bit too early to share the CapEx number beyond this year’s.”
Wei gave dates. TSMC expects N2-family annual capacity to “more than double in 2027.” A14 risk production is “well on track for 2027,” he said, with volume production in 2028. He said Arizona’s second fab will start volume production in 3Q 2027, “slightly ahead of our previous schedule.” He also said TSMC had sent teams to evaluate Texas and was talking with a customer trying to build a fab, Terafab: “We are still in discussion.”
Background: why the guidance comparison matters
In both the July and October releases, TSMC guided revenue in US dollars and tied its margin ranges to an exchange rate assumption, and its results slides print the earlier guidance beside the result. That lets readers check the company against its own numbers. For reference, TSMC’s July slides show second-quarter revenue of US$40.20 billion against a US$39.0 billion to US$40.2 billion guide, gross margin of 67.7% against 65.5%–67.5%, and operating margin of 60.3% against 56.5%–58.5%.
On the memory side of AI chips, see why memory prices surged in 2026, what HBM is and Micron’s fiscal Q4 2026 results.
What could go right / what could go wrong
Both lists use only TSMC’s numbers and its executives’ words.
What could go right
- The Q4 revenue range (US$52.3B–54.3B) would be a 14% sequential rise at the midpoint, per Huang, and the full-year growth outlook moved from “slightly above 40%” to around 44%.
- TSMC expects N2-family capacity to more than double in 2027, and Wei put Arizona’s second fab slightly ahead of its earlier schedule.
- Free cash flow was NT$476.56 billion in the quarter, up from NT$287.36 billion in the second quarter, on the slide’s definition (operating cash flow minus capex).
What could go wrong
- Gross margin fell 1.3 points from the second quarter, and the Q4 guide implies a further 40-basis-point decline at the midpoint, which Huang tied to the 2-nanometer ramp and overseas fabs.
- Huang said TSMC expects dilution from its overseas fabs “to widen to 3%-4% in the next few years” as more U.S. fabs ramp.
- Wei said “consumer and price-sensitive end market segment are being challenged due to the impact of rising component prices and macroeconomic uncertainties,” and that TSMC is being prudent in planning for 2027.
FAQ
Q What was TSMC's Q3 2026 revenue?
A US$46.72 billion, or NT$1,494.24 billion, up 41.2% in US dollars and 50.9% in NT dollars from a year earlier. TSMC had guided to US$44.6 billion to US$45.8 billion in July.
Q Did TSMC beat its own Q3 2026 guidance?
A Revenue (US$46.72 billion) and operating margin (58.7%) came in above the top of the July ranges. Gross margin (66.4%) was inside the 65%–67% range.
Q What is TSMC's Q4 2026 guidance?
A Management expects revenue of US$52.3 billion to US$54.3 billion, gross margin of 65% to 67% and operating margin of 56.5% to 58.5%, based on an exchange rate assumption of 31.8 NT dollars per US dollar.
Q How much of TSMC's revenue came from 2nm and 3nm in Q3 2026?
A 2-nanometer was 8% of wafer revenue and 3-nanometer 33%. Nodes of 7nm and below made up 79%.
Q What is TSMC's 2026 capex budget?
A CFO Wendell Huang reiterated a 2026 capital budget of US$60 billion to US$64 billion on the Oct. 15 call. Third-quarter capex was NT$443.21 billion, which he gave as US$13.8 billion.
Companies in this report: TSMC
Sources
- TSMC Form 6-K for October 2026 (filed Oct. 15, 2026)
- TSMC third-quarter 2026 earnings release (6-K Ex. 99.1, Oct. 15, 2026)
- TSMC 2026 third-quarter earnings conference presentation (6-K Ex. 99.2, Oct. 15, 2026)
- TSMC second-quarter 2026 earnings release with Q3 guidance (6-K Ex. 99.1, July 16, 2026)
- TSMC 2026 second-quarter earnings conference presentation (6-K Ex. 99.2, July 16, 2026)
- TSMC (TSM) Q3 2026 earnings call transcript
- Taiwan Semiconductor Manufacturing Q2 earnings call highlights
- TSMC reports record Q3 profit of $23.55 billion as AI demand drives growth and US expansion plans