AI-generated illustration
TL;DR
- Not released yet: as of 7:30 a.m. ET on October 16, 2026, the IRS had not published its tax year 2027 inflation adjustments, the revenue procedure that sets the 2027 brackets and standard deduction. Its latest news release was IR-2026-122 (October 14).
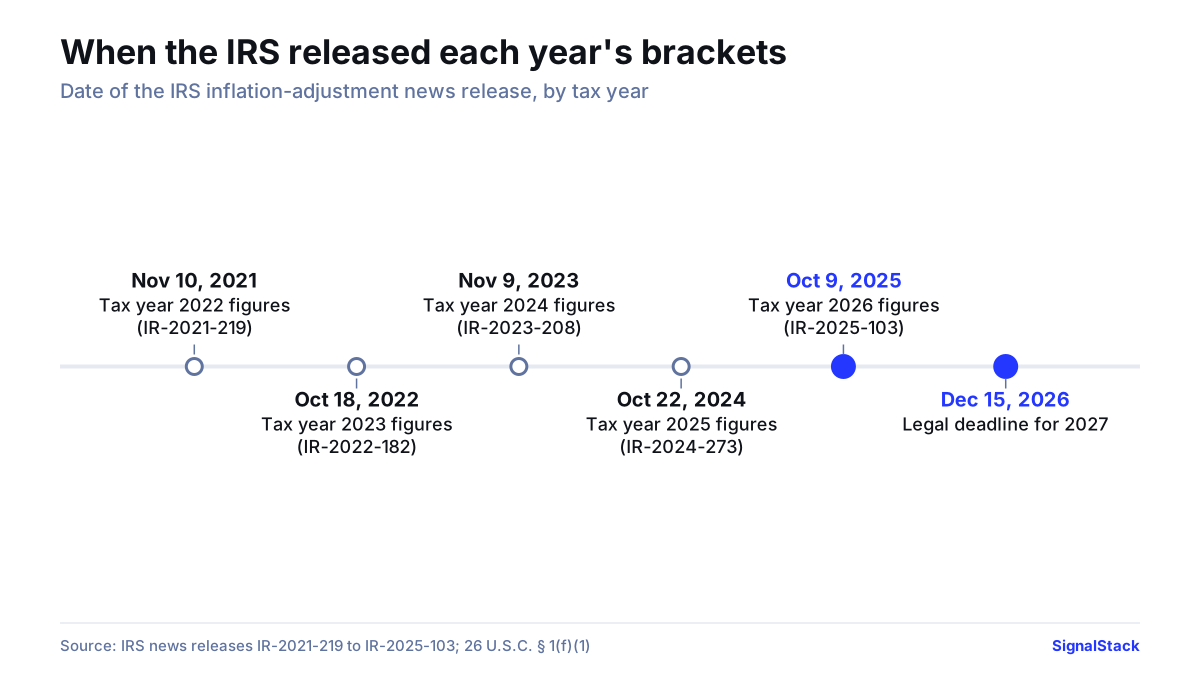
- When it came before: the IRS announced the 2026 figures on October 9, 2025, the 2025 figures on October 22, 2024, and the 2024 figures on November 9, 2023. The tax code (26 U.S.C. § 1(f)(1)) sets a deadline of December 15.
- Already official for 2027: health savings account (HSA) limits of $4,500 for self-only and $9,000 for family coverage, in Rev. Proc. 2026-24.
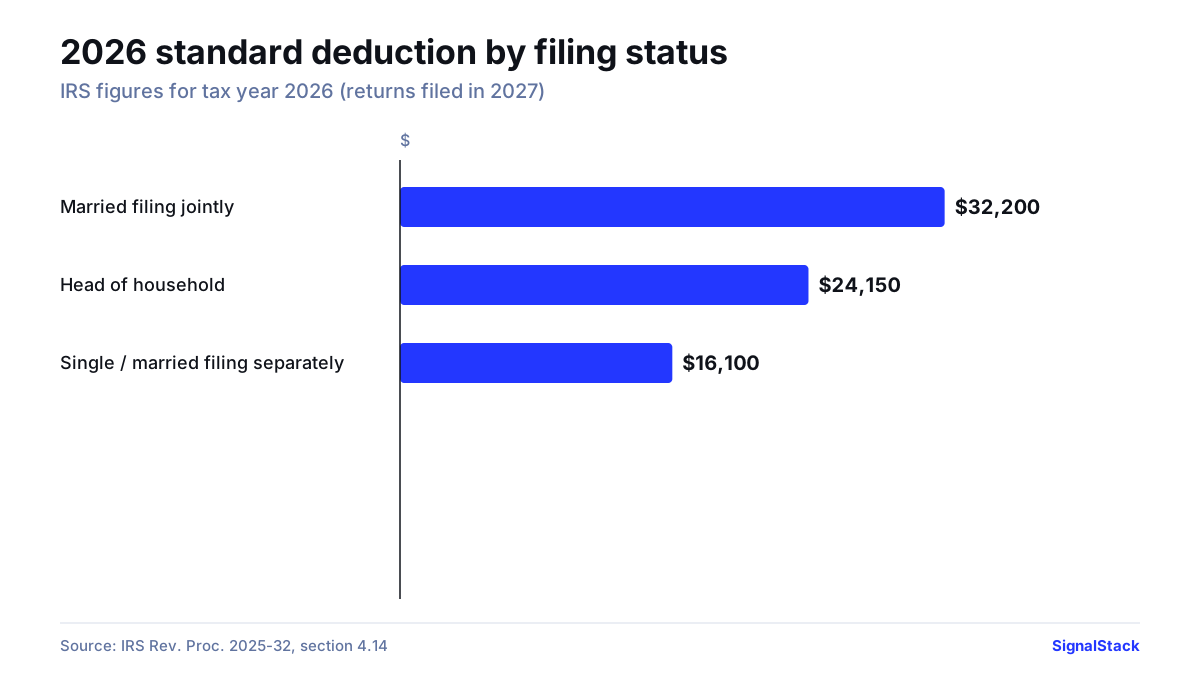
- In force now (2026): standard deduction $16,100 single, $32,200 married filing jointly, $24,150 head of household; rates of 10% to 37%, with the top rate above $640,600 for single filers and $768,700 for joint filers.
This page will be updated with the IRS’s official 2027 figures when they are released.
Where the 2027 figures stand
The IRS publishes each year’s inflation-adjusted amounts in a revenue procedure and a news release. For 2026 that was Rev. Proc. 2025-32 and IR-2025-103. The IRS says the 2026 amounts “generally apply to tax returns filed in 2027,” so the 2027 amounts would generally apply to returns filed in 2028.
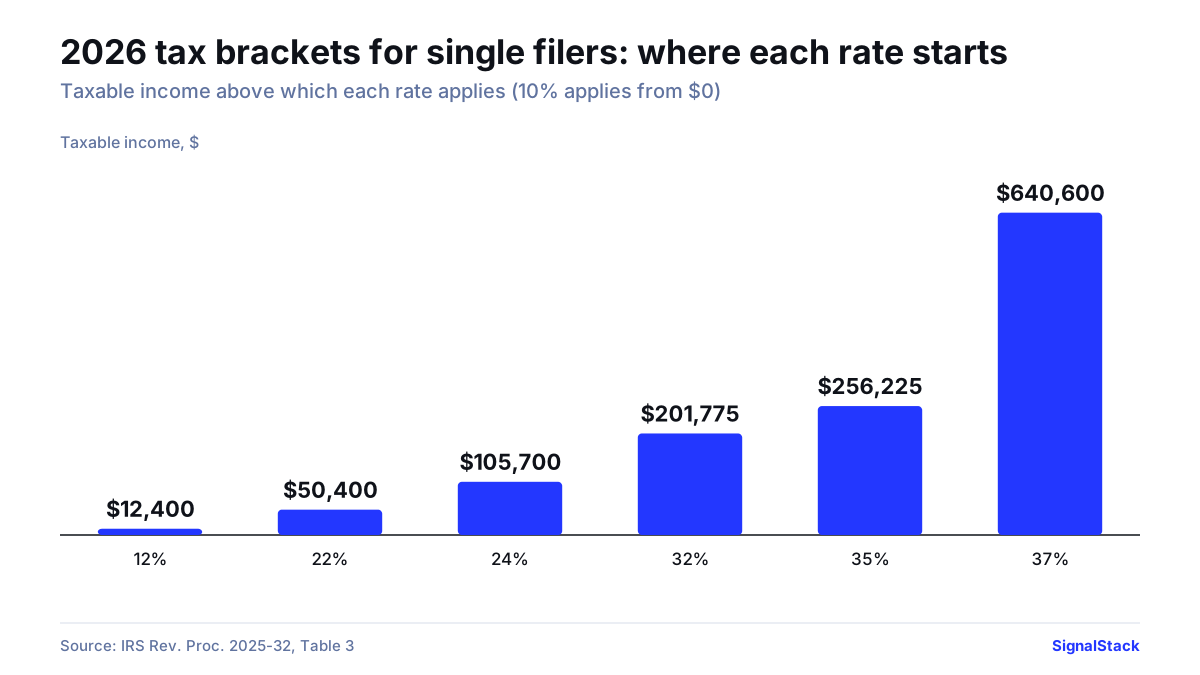
The official 2026 tax brackets (Rev. Proc. 2025-32)
Taxable income ranges by rate, from Tables 1–3 of section 4.01:
| Rate | Single | Married filing jointly | Head of household |
|---|---|---|---|
| 10% | $0–$12,400 | $0–$24,800 | $0–$17,700 |
| 12% | $12,400–$50,400 | $24,800–$100,800 | $17,700–$67,450 |
| 22% | $50,400–$105,700 | $100,800–$211,400 | $67,450–$105,700 |
| 24% | $105,700–$201,775 | $211,400–$403,550 | $105,700–$201,750 |
| 32% | $201,775–$256,225 | $403,550–$512,450 | $201,750–$256,200 |
| 35% | $256,225–$640,600 | $512,450–$768,700 | $256,200–$640,600 |
| 37% | Over $640,600 | Over $768,700 | Over $640,600 |
Married people filing separately use the single thresholds up to the 35% bracket, which ends at $384,350; the 37% rate applies above that. Each rate applies only to the slice of taxable income inside its range.
The 2026 standard deduction
| Filing status | 2025 (as amended by OBBBA) | 2026 |
|---|---|---|
| Single; married filing separately | $15,750 | $16,100 |
| Married filing jointly; surviving spouse | $31,500 | $32,200 |
| Head of household | $23,625 | $24,150 |
The 2026 additional standard deduction for age 65 or older, or blindness, is $1,650 ($2,050 if unmarried and not a surviving spouse). A dependent’s deduction is capped at the greater of $1,350 or earned income plus $450, per the revenue procedure.
How the yearly adjustment is set by law
Section 1 of the Internal Revenue Code sets the rules:
- Deadline. Section 1(f)(1) says the Treasury Secretary “shall prescribe tables” for the next year “[n]ot later than December 15.” Section 1(j)(3)(B) applies that procedure to the current seven-rate tables.
- Index. The cost-of-living adjustment compares the chained consumer price index for all urban consumers (C-CPI-U) for the preceding calendar year with a base year. A year’s C-CPI-U is “the average of the C-CPI-U as of the close of the 12-month period ending on August 31,” per § 1(f)(6)(B). For 2027 that window runs from September 2025 through August 2026, as tax writer Kelly Phillips Erb notes.
- Rounding. Increases that are “not a multiple of $50” are rounded “to the next lowest multiple of $50,” and to $25 for married people filing separately (§ 1(f)(7)). Section 1(j)(3)(B)(ii) extends the $25 rule to single filers, which is why single thresholds such as $256,225 end in 25.
- The One Big Beautiful Bill Act (OBBBA) change. The law, enacted July 4, 2025, made the seven rates permanent, per Rev. Proc. 2025-32. It also limited the newer 2017 base year to the points where brackets “higher than 12 percent” end and brackets “higher than 22 percent” begin. By our reading, the points where the 12% and 22% rates start fall outside that limit and use the statute’s default 2016 base (previously all used 2017), counting one more year of inflation.
By our reading of § 1(j)(3)(B), that last change shows in the 2026 tables. The single 12% threshold rose 4.0% from 2025 ($11,925 to $12,400), while the 37% threshold rose 2.3% ($626,350 to $640,600), by our arithmetic. CNBC Make It reported brackets rising about 4% for lower-income ranges and roughly 2% for higher earners.
OBBBA reset the standard deduction’s base to $15,750, $23,625 and $31,500 for 2025, “adjusted for inflation for taxable years beginning after 2025,” per the revenue procedure.
The missing October 2025 price data
Because of the lapse in appropriations from October 1 to November 12, 2025, “BLS could not publish October 2025 indexes for most CPI series,” the Bureau of Labor Statistics says in its shutdown FAQ, last modified September 16, 2026. The FAQ does not address tax indexing.
Wolters Kluwer says its 2027 projections “are based on an 11-month average of CPI for the period beginning September 2025 through August 2026.” Erb writes that Bloomberg Tax also used an 11-month average because BLS did not publish an October 2025 C-CPI-U value. The IRS’s October 2026 news releases, checked at 7:30 a.m. ET on October 16, do not address the gap.
Projections, not IRS figures
Wolters Kluwer’s projections, from its Federal Tax Weekly of September 17, 2026, use CPI figures released September 11, 2026. They are not official and may differ from what the IRS publishes.
| Wolters Kluwer projection for 2027 | Single | Married filing jointly | Head of household |
|---|---|---|---|
| Standard deduction | $16,600 | $33,200 | $24,950 |
| 10% bracket ends at | $12,800 | $25,600 | $18,250 |
| 37% rate starts above | $661,375 | $793,650 | $661,350 |
Rounding can change a projected figure: Erb reports that Bloomberg Tax’s literal calculation for the head-of-household deduction gives $24,925, though Bloomberg expects the IRS may publish $24,950.
2027 HSA limits are already set
Rev. Proc. 2026-24, posted by the IRS on May 29, 2026, sets the 2027 amounts:
| Item | 2026 | 2027 |
|---|---|---|
| HSA contribution limit, self-only | $4,400 | $4,500 |
| HSA contribution limit, family | $8,750 | $9,000 |
| High-deductible plan minimum deductible, self-only / family | $1,700 / $3,400 | $1,750 / $3,500 |
| High-deductible plan out-of-pocket maximum, self-only / family | $8,500 / $17,000 | $8,700 / $17,400 |
| Excepted benefit HRA maximum | $2,200 | $2,250 |
The 2026 limits come from Rev. Proc. 2025-19.
When the IRS released past years’ figures
What could go right / What could go wrong
What could go right
- Rates are set in current law: OBBBA made the 10%–37% rates permanent, so the yearly revenue procedure adjusts dollar amounts, not rates.
- Some 2027 numbers are known: the HSA limits rise $100 (self-only) and $250 (family), our arithmetic.
What could go wrong
- One month of data is missing: BLS did not publish October 2025 indexes for most series, and the Wolters Kluwer and Bloomberg Tax projections rest on 11 months of data.
- Rounding down: the statute rounds each increase down to a multiple of $50 (or $25), so thresholds can rise slightly less than the index.
- Later law changes: Rev. Proc. 2025-32 covers the code “as in effect on October 9, 2025” and tells taxpayers to consult additional guidance if amendments for 2025 or 2026 are enacted after that date.
Related: CPI release dates, the 2027 Social Security COLA (based on CPI-W) and our Guides section.
FAQ
Q What are the tax brackets for 2027?
A The IRS had not released them as of 7:30 a.m. ET on October 16, 2026. Under current law (OBBBA), the rates stay 10%, 12%, 22%, 24%, 32%, 35% and 37%, and the income thresholds are adjusted for inflation.
Q When will the IRS release 2027 tax brackets?
A As of October 16, 2026, IRS news releases gave no release date. The law sets a December 15 deadline, and the last five releases came between October 9 and November 10.
Q What is the standard deduction for 2027?
A Not yet set by the IRS. For 2026 it is $16,100 for single filers, $32,200 for married couples filing jointly and $24,150 for heads of household. Wolters Kluwer projects $16,600, $33,200 and $24,950 for 2027; those are projections, not IRS figures.
Q What are the 2026 tax brackets?
A For single filers: 10% up to $12,400, 12% to $50,400, 22% to $105,700, 24% to $201,775, 32% to $256,225, 35% to $640,600 and 37% above that. Joint filers' thresholds run from $24,800 to $768,700.
Q What are the 2027 HSA limits?
A $4,500 for self-only coverage and $9,000 for family coverage, up from $4,400 and $8,750, per IRS Rev. Proc. 2026-24.
Sources
- News releases for current month (checked Oct 16, 2026, 7:30 a.m. ET; no tax year 2027 inflation-adjustment release)
- IRS releases tax inflation adjustments for tax year 2026, including amendments from the One, Big, Beautiful Bill (IR-2025-103, Oct 9, 2025)
- Revenue Procedure 2025-32 (2026 inflation-adjusted items)
- Revenue Procedure 2026-24 (2027 HSA and HDHP amounts)
- Revenue Procedure 2025-19 (2026 HSA and HDHP amounts)
- IRS releases tax inflation adjustments for tax year 2025 (IR-2024-273, Oct 22, 2024)
- IRS provides tax inflation adjustments for tax year 2024 (IR-2023-208, Nov 9, 2023)
- IRS provides tax inflation adjustments for tax year 2023 (IR-2022-182, Oct 18, 2022)
- IRS provides tax inflation adjustments for tax year 2022 (IR-2021-219, Nov 10, 2021)
- 26 U.S. Code § 1 — Tax imposed (subsections (f) and (j), with 2025 amendment notes)
- 2025 federal government shutdown impact on the Consumer Price Index (FAQ, last modified Sep 16, 2026)
- Wolters Kluwer Projects Inflation Amounts for 2027 (Federal Tax Weekly, Issue 38, Sep 17, 2026)
- Your First Look at 2027 Tax Brackets, Standard Deduction Amounts and More (Sep 12, 2026)
- IRS announces new federal income tax brackets for 2026
- Here are the new federal income tax brackets for 2026
- IRS releases income tax brackets and standard deductions for 2026