# Tesla's $30 Billion Credit Facilities: What the 8-K Says
> Tesla signed $30B of unused bank facilities and ended a $5B revolver. The 8-K's draw rules, maturities, fees and covenants, set against its June 30 10-Q.
Tesla signed three new bank credit agreements worth a combined $30.0 billion on September 29, 2026, and reported them in a [Form 8-K](/glossary/form-8-k/) filed the same day. The package replaces a $5.0 billion revolving credit line from 2023 that had nothing drawn on it. None of the new money has been borrowed either, and Tesla says it does not currently plan to draw on it in 2026.
## TL;DR
- **$30 billion, none of it drawn.** A $20.0 billion three-year delayed-draw term loan (Citibank as agent), plus an $8.0 billion five-year revolver and a $2.0 billion 364-day revolver (Wells Fargo as agent for both). All three are senior unsecured.
- **Six times the line it replaced, with a higher liquidity floor.** The old revolver was $5.0 billion. The minimum-liquidity covenant rises from $1.0 billion, as disclosed in the 2023 8-K, to $5.0 billion under the new agreements.
- **Large next to its June 30 debt.** At June 30, 2026, Tesla's [10-Q](/glossary/form-10-q/) showed $43.52 billion of cash and short-term investments and $9.08 billion of debt principal, almost all of it non-recourse subsidiary debt.
## What happened
The 8-K reports three substantive items: Item 1.01 (new material agreements), Item 1.02 (the terminated revolver) and Item 2.03 (a new direct financial obligation). It is signed by CFO Vaibhav Taneja and attaches no credit agreements. Tesla says the full agreements will be filed as exhibits to its 10-Q for the quarter ending September 30, 2026.
Dow Jones and Reuters reported the filing shortly after 5 p.m. ET that day. Reuters tied it to Tesla's spending, writing that the company "expects to direct much of its record spending this year toward AI compute infrastructure, solar cell-manufacturing capacity and a semiconductor fabrication project with SpaceX, as well as other expansion areas." Teslarati and Drive Tesla Canada linked the money to Cybercab, Semi and Optimus, and Electrek framed it as borrowing to cover falling profits and rising capital spending. Those are the outlets' readings. We searched the 8-K text: it does not mention Cybercab, Optimus, robots, AI or capital expenditure.
## What the 8-K says
| | Term Loan Facility | Five-Year Revolver | 364-Day Revolver |
|---|---|---|---|
| Size | $20.0 billion | $8.0 billion | $2.0 billion |
| Administrative agent | Citibank, N.A. | Wells Fargo Bank, N.A. | Wells Fargo Bank, N.A. |
| How it works | Delayed draw: up to 10 draws in the first 18 months | Borrow, repay, reborrow | Borrow, repay, reborrow |
| Ends | Loans due September 29, 2029 | September 29, 2031 | September 28, 2027 |
| Options | None disclosed | Up to two one-year extensions (subject to conditions); up to $500 million of letters of credit | Term-out, subject to conditions: push the maturity of outstanding loans back one year |
| Currencies | US dollars (only USD pricing disclosed) | US dollars, pounds sterling, euros | US dollars |
| Fee on unused amount | Ticking fee | Commitment fee | Commitment fee |
Source: Tesla Form 8-K, September 29, 2026.
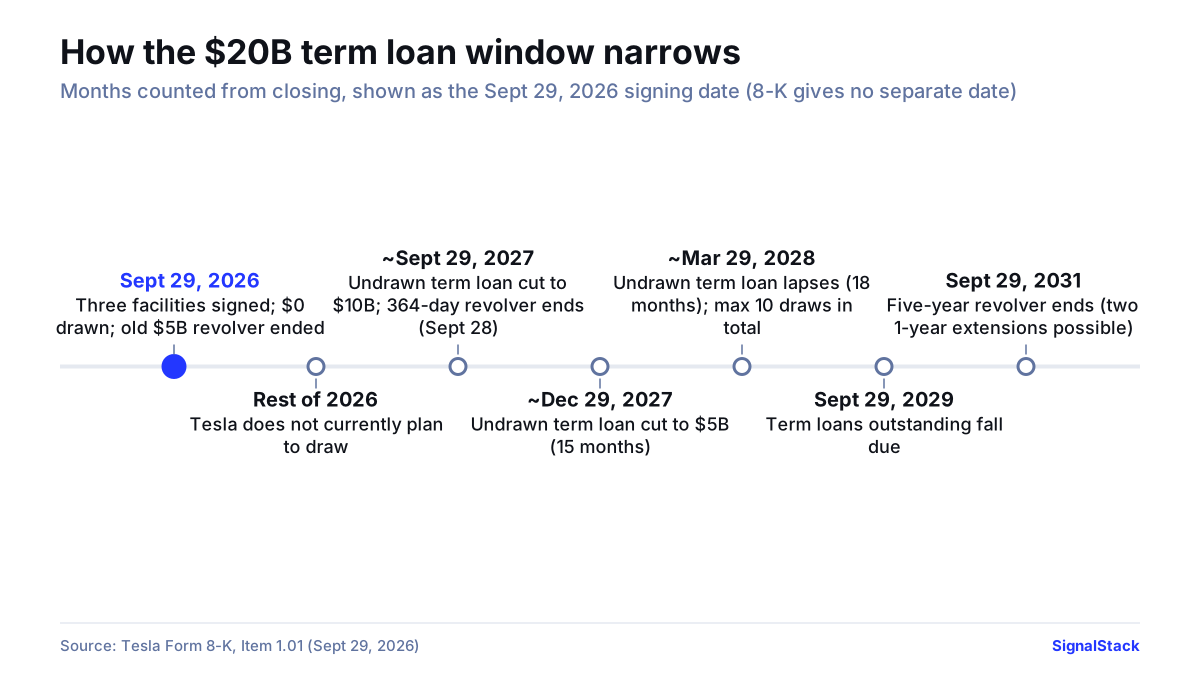
**1. The term loan shrinks on a fixed schedule.** Unused term-loan capacity steps down by itself: to $10.0 billion one year after closing, to $5.0 billion at 15 months, and to zero at 18 months. The 8-K gives no separate closing date. If it is the September 29, 2026 signing date, the cuts land around late September 2027, late December 2027 and late March 2028. Subject to the agreements' conditions, which are not yet public, the full $20 billion can be drawn from closing, including in 2026, but Tesla says it does not currently plan to draw in 2026. If it sticks to that plan, the full $20 billion would remain available only until about late September 2027, when undrawn capacity drops to $10 billion.
**2. The revolvers can grow.** Tesla may add up to $4.0 billion of commitments across the two revolvers, subject to conditions, for a possible total of $14.0 billion. The 2023 revolver's accordion was $2.0 billion.
**3. Pricing is tied to Tesla's credit rating, and the numbers are not public yet.** Dollar loans float at Term SOFR or an alternate base rate, at Tesla's choice, plus a margin. Sterling loans use SONIA and euro loans use adjusted EURIBOR. The margins, the revolvers' commitment fee and the term loan's ticking fee all move with the rating on Tesla's senior unsecured long-term debt (or, in some cases, its issuer rating). Fees are paid quarterly. The 8-K gives no basis points. For reference, Tesla's 2025 10-K put the undrawn fee on the old revolver, at the time, at 0.125% a year.
**4. Covenants.** The agreements limit liens and debt at Tesla's "restricted subsidiaries," with exceptions, and require at least $5.0 billion of consolidated liquidity as the agreements define it. On an event of default, lenders may cancel their commitments and demand immediate repayment.
**5. Use of proceeds.** Loans and letters of credit may fund general corporate purposes or anything else the agreements do not prohibit. The 8-K names no project.
The $20 billion term loan is a shrinking window; months are counted from closing, shown here as the Sept 29, 2026 signing date. Source: Tesla Form 8-K, Item 1.01 (Sept 29, 2026).
## What was replaced
Tesla ended its January 20, 2023 revolver (Citibank as agent, $5.0 billion, due January 20, 2028). Nothing was outstanding and there was no early termination penalty. Some of its lenders, or their affiliates, are in the new syndicates; the 8-K does not name them.
| | 2023 revolver (terminated) | 2026 facilities (new) |
|---|---|---|
| Committed | $5.0 billion | $30.0 billion ($10.0 billion revolving) |
| Accordion | Up to $2.0 billion more | Up to $4.0 billion more (revolvers) |
| Minimum liquidity covenant | $1.0 billion (as disclosed in the 2023 8-K) | $5.0 billion |
| Latest maturity | January 20, 2028 | September 29, 2031 |
| Drawn at signing | $0 | $0 |
Sources: Tesla Form 8-Ks filed January 25, 2023 (agreement dated January 20) and September 29, 2026.
The 2023 deal followed the same pattern: its 8-K reported the termination of an amended and restated 2019 asset-based loan agreement, also with nothing drawn.
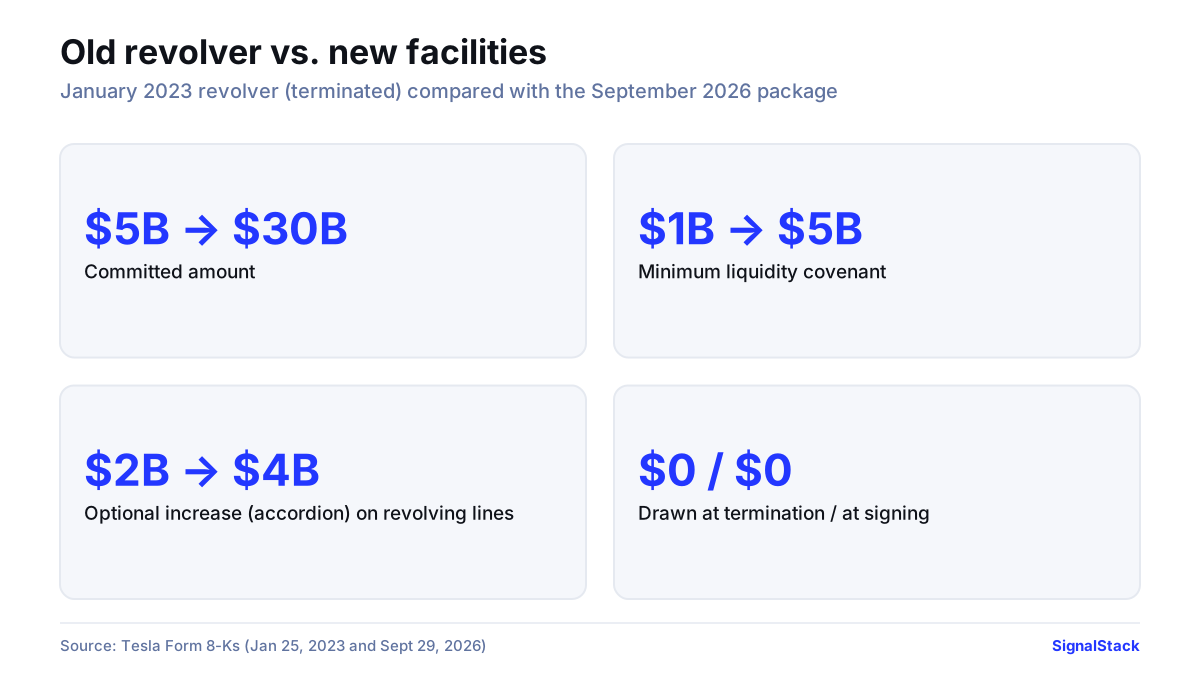
The new package is six times larger and carries five times the minimum-liquidity covenant disclosed for the old line in 2023. Source: Tesla Form 8-Ks (Jan 25, 2023 and Sept 29, 2026).
## Set against Tesla's 10-Q
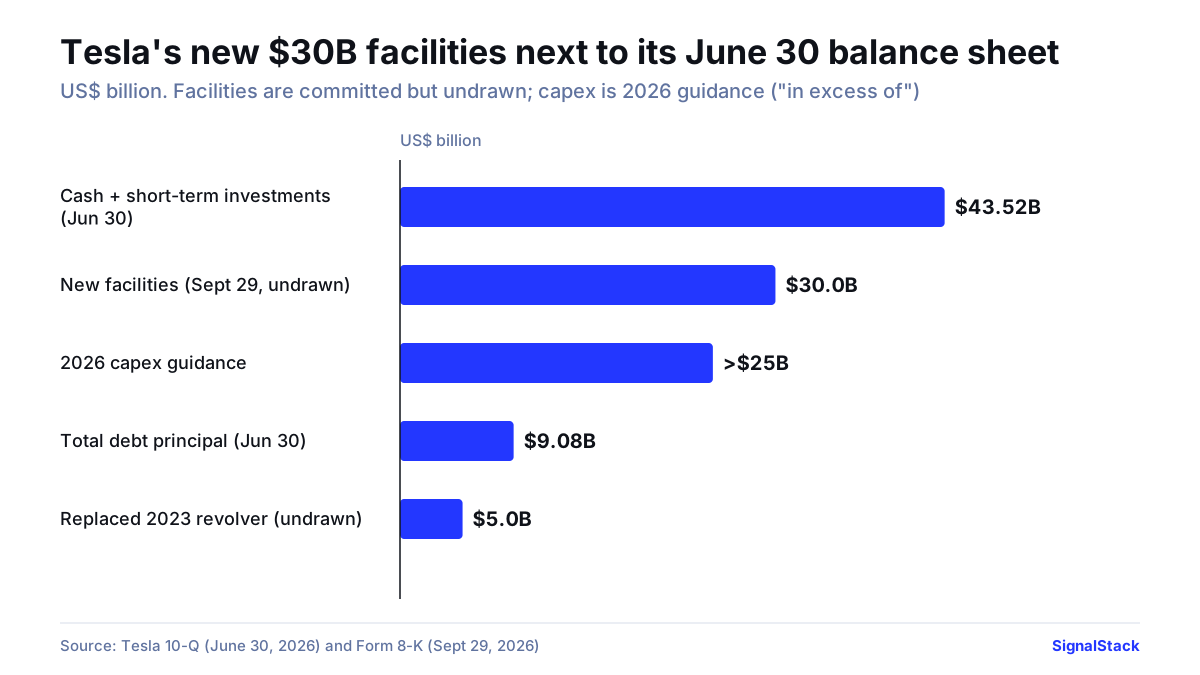
Tesla's June 30, 2026 balance sheet showed $15.22 billion of cash and cash equivalents and $28.31 billion of short-term investments, or $43.52 billion combined, a total the 10-Q itself reports. Debt principal was $9.08 billion; the current portion of debt (net carrying value) was $1.34 billion.
Almost none of that debt is recourse to Tesla's general assets. Note 8 of the 10-Q lists just $2 million of recourse debt. The rest is non-recourse, which the 10-Q defines as debt that is recourse only to its subsidiaries' assets: a $5.89 billion China working capital facility, $2.37 billion of automotive asset-backed notes, $0.71 billion of energy asset-backed notes and $0.12 billion of cash equity debt. The old $5.0 billion revolver appeared in the recourse section as unused capacity.
The comparison the coverage we reviewed skips: the $20 billion term loan alone is more than twice Tesla's total June 30 debt. If every facility were fully drawn, the $30 billion would be about 3.3 times that debt (our arithmetic). Tesla says it has no such plan for 2026.
The unused $30 billion is more than three times Tesla's June 30 debt and smaller than its cash and short-term investments. Source: Tesla 10-Q (June 30, 2026) and Form 8-K (Sept 29, 2026).
### Why spending matters here
Tesla's Q2 10-Q says it expects 2026 capital expenditures above $25 billion, "driven by our AI initiatives," including compute infrastructure and data centers, production lines and its fleet of company-operated AI-enabled assets. Capital spending was $8.53 billion for all of 2025, per the 10-K.
| Period | Operating cash flow | Capital expenditures |
|---|---|---|
| Q1 2026 | $3.94 billion | $2.49 billion |
| Q2 2026 | $4.70 billion | $5.79 billion |
| First half 2026 | $8.63 billion | $8.28 billion |
Sources: Tesla 10-Qs for March 31 and June 30, 2026. Q2 is our subtraction of Q1 from the six-month totals.
In Q2, capital spending exceeded operating cash flow by about $1.09 billion. If full-year spending meets the "in excess of $25 billion" guidance, at least $16.7 billion would fall in the second half (our arithmetic). Tesla's own 10-Q says periods of heavy capital spending "will necessitate additional funding beyond our operating cash flow." It lists drawdowns on existing or new debt facilities among the ways it may raise money.
## Background: how these facilities work
A delayed-draw term loan is committed money taken in pieces over a set window; the ticking fee pays banks to hold the unused part open. A revolver is a corporate credit line that can be borrowed, repaid and borrowed again. All three float with benchmark rates, so the cost of any draw would move with short-term market rates (see our report on the [Fed's September 2026 decision](/blog/fed-rate-hike-september-2026-statement-dot-plot/)).
For Tesla's reported results and filings, see the [Tesla company hub](/company/tesla/), [Tesla earnings](/earnings/tesla/) and [Tesla insider filings](/insiders/tesla/). More coverage: [Markets & Policy](/category/markets-policy/) and our 8-K explainer on [Nvidia's $150 billion buyback](/blog/nvidia-150-billion-buyback-authorization/).
## What could go right / What could go wrong
**What could go right**
- Tesla, Inc. has committed bank money, on terms not yet filed, if spending outruns operating cash flow, a gap its 10-Q says heavy capex periods can open.
- Margins and fee rates are tied to Tesla's credit rating, so an upgrade would carry through to them.
**What could go wrong**
- A downgrade would carry through the same way, on fees and on any drawn amounts.
- Drawn debt floats with Term SOFR (or an alternate base rate), SONIA or EURIBOR, so higher rates mean higher interest cost.
- Until Tesla borrows, the ongoing costs the 8-K describes are the ticking fee and commitment fees.
- The $5.0 billion liquidity covenant is five times the old one as disclosed in 2023, and its definition is not yet public.
- Term-loan capacity shrinks on a set schedule and lapses 18 months after closing.
- Margins, fee rates, lender names and full covenants are not public at least until the Q3 10-Q exhibits are filed.
## FAQ
Q How much did Tesla borrow in its $30 billion credit deal?
A Nothing yet. The 8-K says no loans were outstanding as of September 29, 2026, and Tesla has no current plan to borrow under them this year.
Q Which banks are behind Tesla's new credit facilities?
A Citibank, N.A. is administrative agent for the $20 billion term loan, and Wells Fargo Bank is agent for the $8 billion and $2 billion revolvers. The 8-K does not list the other lenders.
Q What is Tesla's $30 billion credit line for?
A The 8-K allows use for general corporate purposes and names no project. Reuters and others linked it to Tesla's 2026 capital spending plans, which Tesla guided above $25 billion.
Q What credit agreement did Tesla terminate?
A Its $5.0 billion revolving credit agreement dated January 20, 2023, with Citibank as agent and a January 2028 maturity. Nothing was drawn and there was no termination penalty.
Q What interest rate will Tesla pay on the new facilities?
A The 8-K gives no figures. Dollar loans float at Term SOFR or a base rate plus a margin that depends on Tesla's credit rating; the full terms will be filed with the Q3 2026 10-Q.