# Share Buybacks Explained: Authorization vs Actual Repurchases
> A buyback authorization is permission, not purchases. How to read the 10-Q repurchase table, what Rule 10b-18 and the 1% excise tax do, with a real example.
**TL;DR**
- A buyback authorization is a board's permission to repurchase stock up to a limit. It is not a purchase, and it may have no expiration date (Item 703 asks companies to footnote "the expiration date (if any)"). What a company actually bought shows up later, in a monthly table in its 10-Q and 10-K.
- That table follows SEC Regulation S-K Item 703 and has four columns: shares bought, average price, shares bought under announced programs, and how much the programs still allow. A 2023 SEC rule that would have required daily repurchase data, disclosed quarterly or semi-annually depending on the issuer, was vacated by a federal appeals court in December 2023, so the monthly table remains the standard.
- Two other rules shape buybacks: Rule 10b-18, a voluntary safe harbor with four daily conditions on how a company buys, and a 1% federal excise tax on the value of stock a publicly traded U.S. company repurchases, reduced by stock it issues.
## Authorization vs repurchase
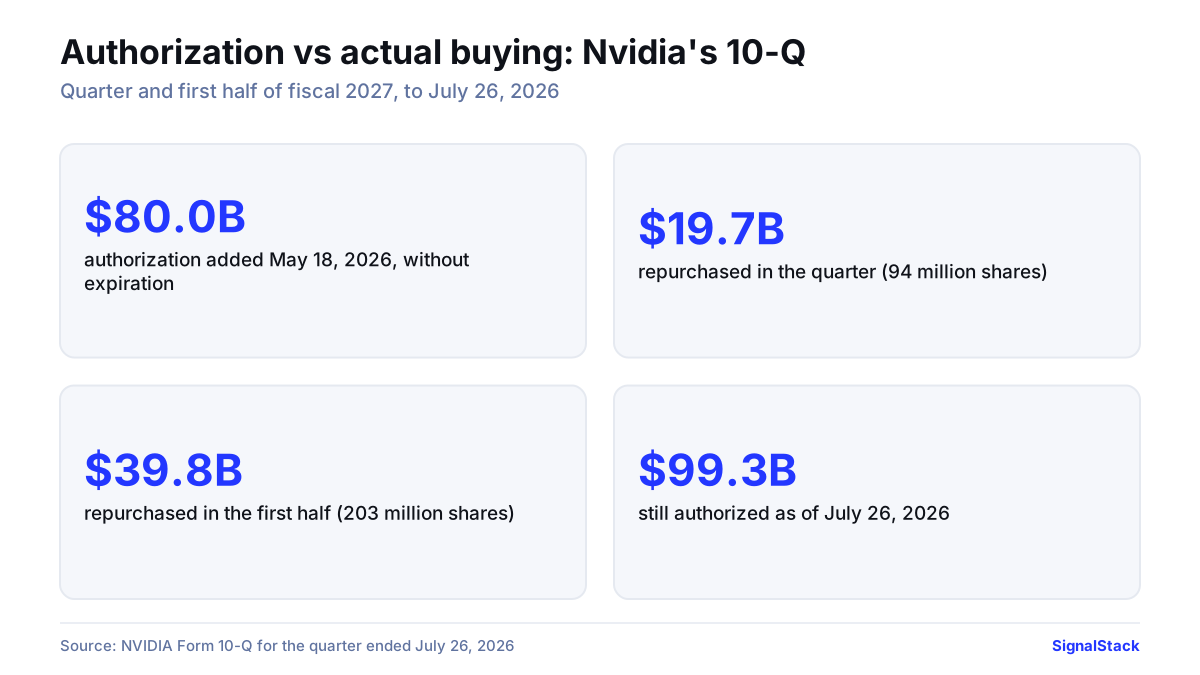
A buyback announcement like Nvidia's on May 20, 2026, which disclosed that its board had approved an additional $80.0 billion of repurchase authorization on May 18, is permission to buy more, up to a limit. None of that new amount has been spent at the moment of approval. The company then buys when and if it chooses, and the remaining room shrinks as it does.
Nvidia's latest 10-Q shows the difference. It says the board approved an additional $80.0 billion of repurchase authorization on May 18, 2026, "without expiration," and that as of July 26, 2026 the company was authorized, "subject to certain specifications," to repurchase up to $99.3 billion more. In the same quarter, it actually bought 94 million shares for $19.7 billion, and 203 million shares for $39.8 billion over the first half of its fiscal year. The 10-Q adds that the program "may be suspended at any time." For what came next, see our report on [Nvidia's $150 billion buyback increase](/blog/nvidia-150-billion-buyback-authorization/).
An authorization sets a ceiling; the 10-Q shows what was actually bought. Source: NVIDIA Form 10-Q for the quarter ended July 26, 2026.
## How to read the repurchase table
Item 703 of Regulation S-K requires a table titled "Issuer Purchases of Equity Securities." In a 10-Q it appears under Part II, Item 2 (as in Nvidia's filing). It has one row per month of the quarter and four columns:
| Column | What it shows | What to watch |
|---|---|---|
| (a) Total number of shares purchased | Every repurchase in the month, under an announced program or not | A footnote must give the number bought outside announced programs and how (open market, tender offer, other) |
| (b) Average price paid per share | The average for the month | Check the footnote for what it includes or excludes |
| (c) Shares purchased under publicly announced plans or programs | The part of (a) that counts against the authorization | If (c) is smaller than (a), read the footnote |
| (d) Maximum number, or approximate dollar value, that may yet be purchased | Remaining room under all announced programs combined | It drops as the company buys and jumps when the board adds authorization |
Footnotes must also give, for each program, the date it was announced, the amount approved, any expiration date, any program that expired during the period, and any the company has decided to end before expiration or under which it does not intend to make further purchases. The rule also says to disclose all purchases covered by the item, including those that fall outside the Rule 10b-18 safe harbor.
## A real example: Nvidia's quarter to July 26, 2026
Here is the table from Nvidia's 10-Q for the second quarter of fiscal 2027:
| Period | Shares purchased (millions) | Average price paid | Under announced program (millions) | May yet be purchased (billions) |
|---|---|---|---|---|
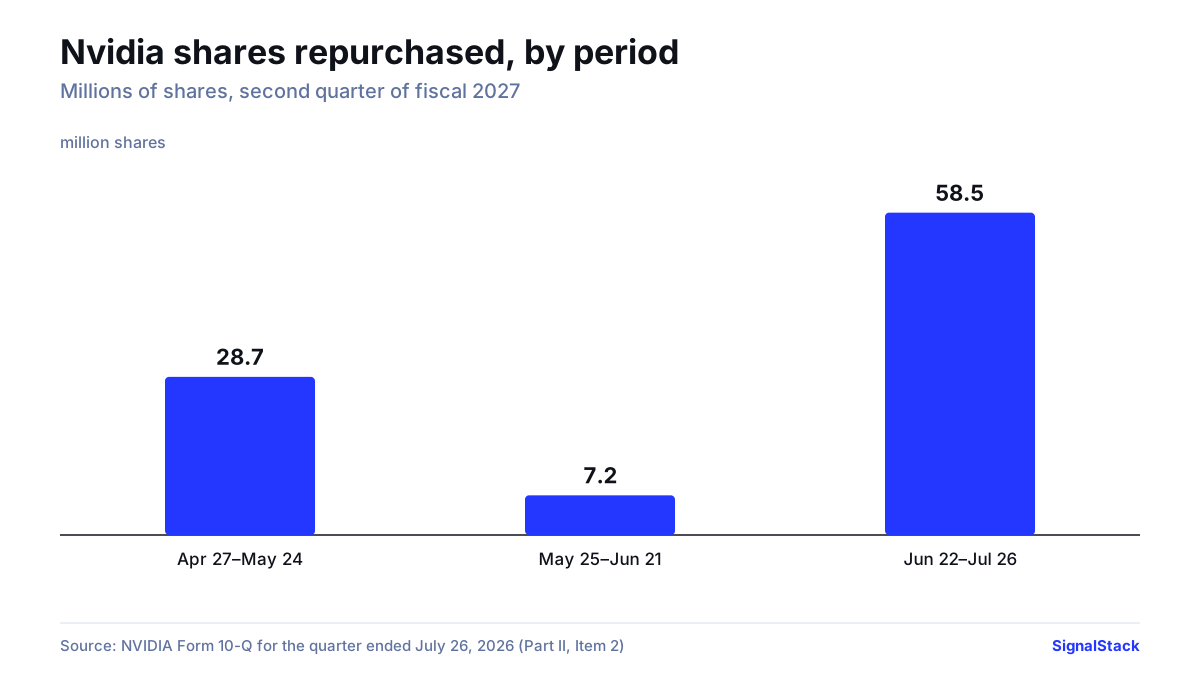
| Apr 27 – May 24, 2026 | 28.7 | $214.32 | 28.7 | $112.7 |
| May 25 – Jun 21, 2026 | 7.2 | $211.29 | 7.2 | $111.1 |
| Jun 22 – Jul 26, 2026 | 58.5 | $202.40 | 58.5 | $99.3 |
| Total | 94.4 | | 94.4 | |
Three things stand out. Columns (a) and (c) match in every month, so every share counted here was bought under the announced program. Column (d) shows $112.7 billion at May 24, after the $80.0 billion the board added on May 18, then $111.1 billion and $99.3 billion as buying continued through July 26. And the footnote says the average price includes broker commissions but leaves out the company's liability under the 1% excise tax.
Monthly buying can vary widely inside one quarter. Source: NVIDIA Form 10-Q for the quarter ended July 26, 2026 (Part II, Item 2).
A few paragraphs below the table, Nvidia reports something the table does not include: it withheld about 12 million shares, worth $2.4 billion, in the quarter through net share settlement to cover employees' tax obligations on equity awards. Those shares also reduce the share count (the 10-Q's statement of shareholders' equity has a "Tax withholding related to common stock" line), so read the paragraphs and statements around the table, not just the table.
## Rule 10b-18: the safe harbor
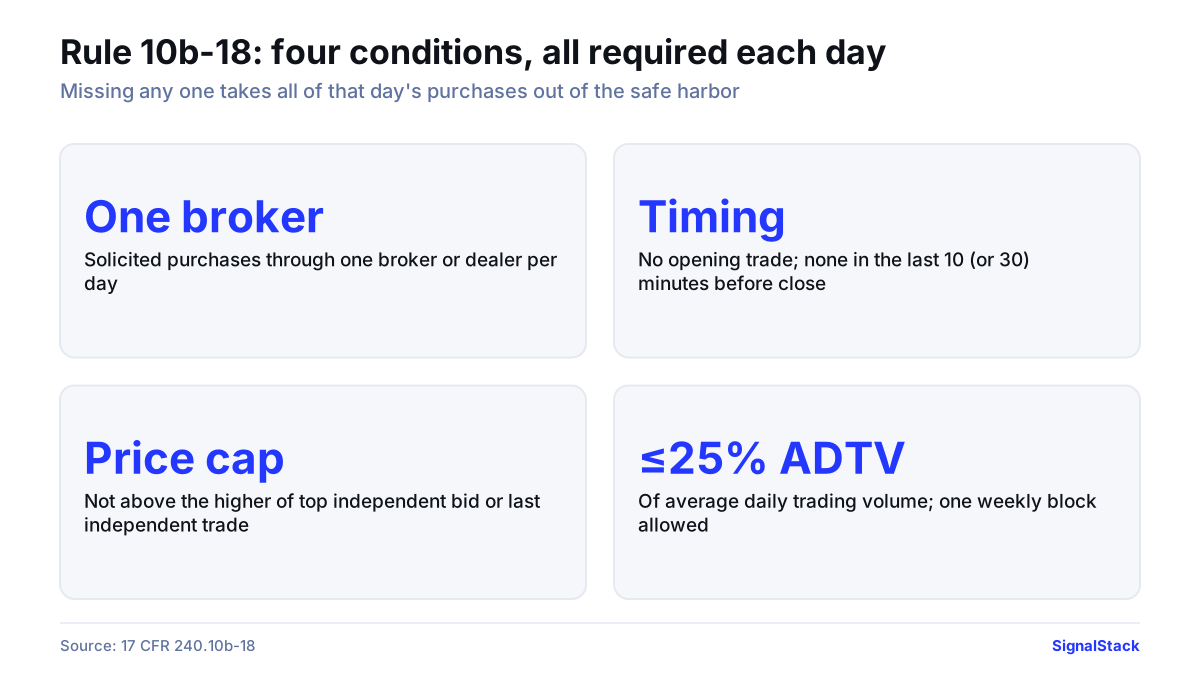
Rule 10b-18 gives a company a "safe harbor" from manipulation claims based on the manner, timing, price and volume of its open-market repurchases. Its preliminary note says compliance is voluntary, and that to be covered, a company's purchases must meet all four conditions every day; missing one takes all of that day's purchases out of the safe harbor. The four conditions, in short:
1. **One broker or dealer.** Solicited purchases on a given day go through a single broker or dealer.
2. **Timing.** No purchase may be the opening reported trade, and none may come in the last 10 minutes before the scheduled close for stocks with average daily trading value of at least $1 million and a public float of at least $150 million; for all other stocks the cutoff is 30 minutes.
3. **Price.** No higher than the highest independent bid or the last independent trade price, whichever is higher.
4. **Volume.** No more than 25% of the stock's average daily trading volume on a single day, with one block purchase a week allowed in place of that limit.
Missing any one condition removes that day's purchases from the safe harbor. Source: 17 CFR 240.10b-18.
Nvidia's 10-Q says it may repurchase in the open market, in privately negotiated deals, under a Rule 10b5-1 trading plan, or through structured agreements "in compliance with Rule 10b-18."
## The 1% excise tax
Section 4501 of the Internal Revenue Code taxes a "covered corporation," a U.S. company whose stock trades on an established securities market, at 1% of the fair market value of stock it repurchases during the year. The amount is reduced by the fair market value of stock the company issues in that year, including stock issued or provided to employees. There are exceptions, among them years in which repurchases total $1 million or less. The IRS's Form 7208, filed with the quarterly Form 720, is used to figure the tax. As Nvidia's footnote shows, a company's reported average price may leave this tax out; Nvidia's 10-Q says elsewhere that the excise tax is included in its share repurchase cost and was not significant for the period.
## The 2023 rule that didn't stick
On May 3, 2023, the SEC adopted a "Share Repurchase Disclosure Modernization" rule (Release No. 34-97424); its press release said companies would have had to report day-by-day repurchase data, filed each quarter or half-year depending on the kind of issuer. In a Feb. 9, 2024 notice, the SEC says the U.S. Court of Appeals for the Fifth Circuit vacated it on Dec. 19, 2023, in *Chamber of Commerce of the USA v. SEC*, and that disclosure requirements "revert to those in effect prior to the Final Rule’s effective date." The current Item 703 on eCFR cites an April 8, 2024 Federal Register entry, and its table is the monthly one described above.
For how buyback disclosures fit into a company's other filings, see our guides to the [Form 10-Q](/glossary/form-10-q/) and to [earnings season](/blog/earnings-season-explained-8-k-10-q-guidance-non-gaap/), and our [Nvidia company page](/company/nvidia/).
## What could go right / What could go wrong
When reading buyback numbers:
- **What helps:** the monthly table, its footnotes, and the paragraphs around it give actual shares, prices and remaining authorization, so an announced headline number can be checked against what was bought.
- **What can mislead:** an authorization can sit unused or be suspended; the table's average price may exclude the excise tax; and shares withheld for employee taxes or issued under stock plans can be reported elsewhere, so the table alone does not show the change in shares outstanding.
## FAQ
Q What is the difference between a buyback authorization and a buyback?
A An authorization is the board's permission to repurchase up to a set amount, sometimes with no expiration date. The actual repurchases are reported afterward in the monthly "Issuer Purchases of Equity Securities" table in the company's 10-Q or 10-K.
Q Where do I find how many shares a company bought back?
A In the 10-Q, under Part II, Item 2, in the table required by Regulation S-K Item 703. It lists shares purchased, average price, shares bought under announced programs and the amount still available, month by month.
Q Is there a tax on stock buybacks?
A Yes. Section 4501 of the Internal Revenue Code imposes a 1% excise tax on the fair market value of stock a covered U.S. corporation repurchases, reduced by the value of stock it issues during the year. It is figured on IRS Form 7208.
Q Do companies have to report buybacks daily?
A No. The SEC's 2023 rule requiring daily repurchase data was vacated by the Fifth Circuit on Dec. 19, 2023, and the SEC says the earlier requirements apply, which call for monthly figures each quarter.